Money Apps and Habits: Automate Your Way to Wealth in 2026
Most people think building wealth requires more discipline. In reality, it requires fewer decisions — and that is exactly what modern money apps deliver. When your savings, bill payments, and investments happen automatically, willpower stops being the bottleneck. This article is not another feature roundup. It is a practical playbook for using automation to rewire your financial habits in 2026, based on the systems that actually stick.
Behavioral research has shown for years that default settings shape behavior more than intentions do. The Consumer Financial Protection Bureau publishes free tools confirming that automatic, “set it and forget it” systems outperform manual effort for the vast majority of households. Money apps simply turn that principle into a tap on your phone.
Why Money Apps Beat Willpower Every Time
Willpower is a finite resource. It fades by the end of a long day, right when the food-delivery button looks most tempting. Automation sidesteps the problem entirely by acting before you can talk yourself out of a good decision.
Consider the difference between two savers:
- The manual saver promises to “move whatever is left” at month’s end. Usually, nothing is left.
- The automated saver routes 10% into savings the moment a paycheck lands. The money is gone before it can be spent.
Over a year, the automated saver wins by a landslide — not because they are more disciplined, but because their system does the work. That is the core promise of good money apps.
The Four Habits to Automate First
1. Pay yourself before anyone else
Set an automatic transfer to a separate high-yield savings account for the day after payday. Treat it like a non-negotiable bill. Even $50 a paycheck builds a meaningful buffer over a year.
2. Never miss a due date
Late fees and interest quietly drain hundreds of dollars a year. Schedule automatic minimum payments on every card and loan, then pay extra manually when you can. This protects your credit score without any monthly effort.
3. Round up your spare change
Round-up features invest the difference between a purchase and the next whole dollar. A $4.30 coffee sends $0.70 into an index fund. It feels invisible, yet it can add hundreds to your portfolio annually.
4. Audit subscriptions automatically
Let an app track recurring charges and flag price increases. Cancelling two forgotten subscriptions often pays for every other tool in your stack.
Manual Money Management vs. Automated Systems
| Task | Manual approach | Automated with money apps |
|---|---|---|
| Saving | Whatever is left over | Fixed % moved on payday |
| Bills | Remember each due date | Auto-pay + reminders |
| Investing | Occasional lump sums | Recurring round-ups |
| Budget review | Rarely happens | Weekly auto-summary |
| Consistency | Depends on mood | Runs regardless |
How Do You Build an Automated Money System?
You do not need a dozen tools. You need a simple, layered system that runs itself. Here is the sequence I recommend:
- Open a dedicated savings account separate from your everyday checking.
- Automate one transfer for the day after payday — start small if money is tight.
- Turn on auto-pay for the minimum on every recurring bill.
- Enable round-up investing on your primary spending account.
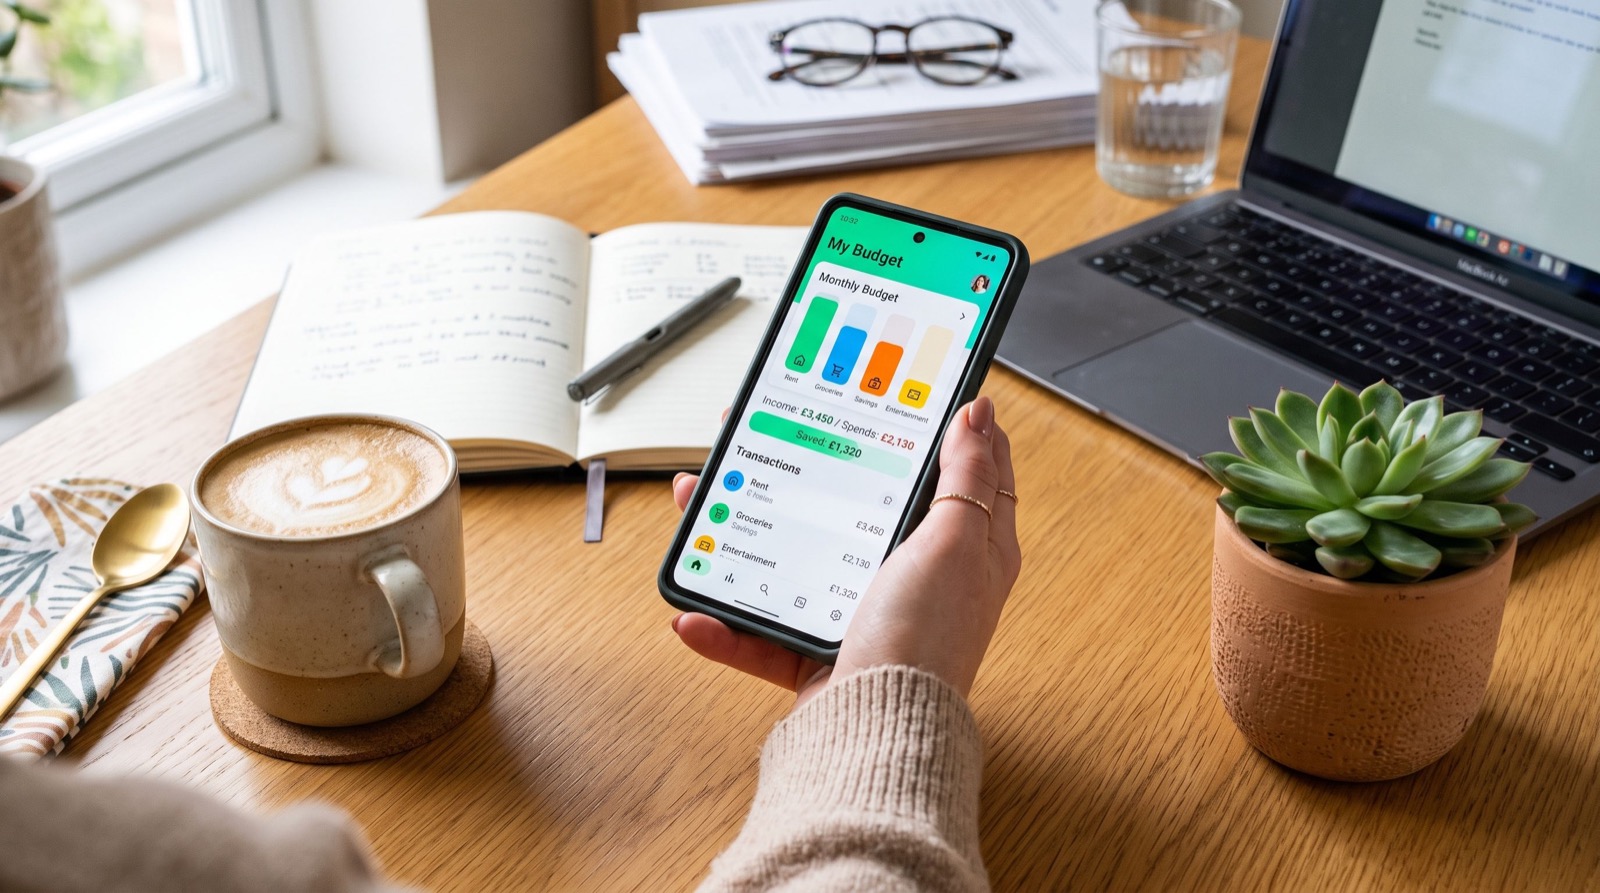
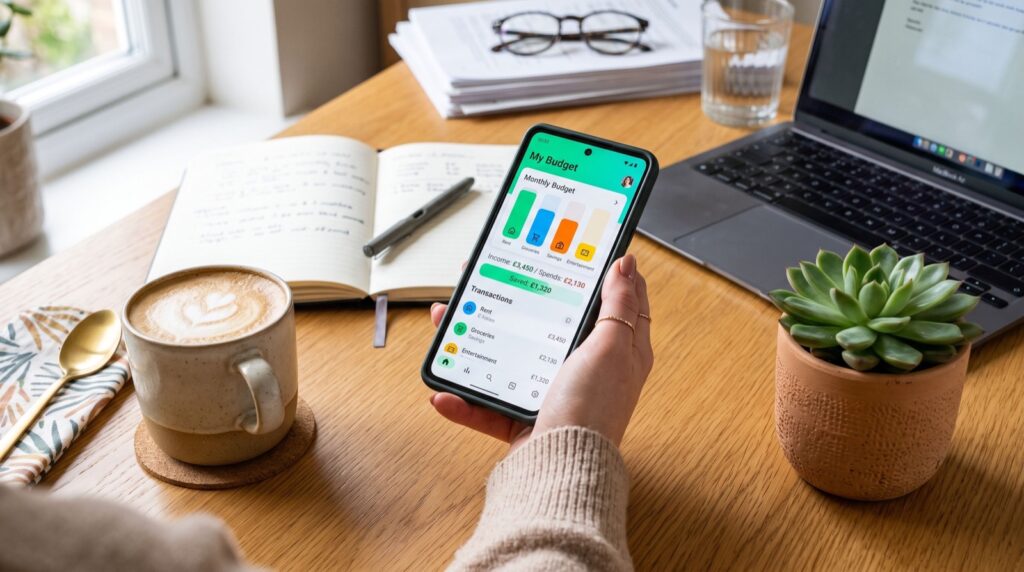
- Schedule a five-minute weekly review using your app’s summary screen.
Choosing the right tools is where many people stall. A well-organized directory of money apps makes it easy to match a tool to each habit, and the curated list of the best money apps is a solid place to compare features before you commit. If you would rather delegate the setup, working with reputable service experts can get the entire automated stack configured correctly the first time.
An Original Tip: The 48-Hour Automation Rule
Here is something I learned the hard way. When you set up a new automated transfer, do not touch it for 48 hours — but then check your account. Automation only works if the amounts match your real cash flow. If that first transfer nearly overdrafts you, lower it immediately rather than abandoning the habit.
The goal is a transfer large enough to matter but small enough that you never feel forced to reverse it. When you find that number, automation becomes truly invisible, and invisible habits are the ones that last for years.
Common Mistakes to Avoid
- Over-automating too fast. Add one habit at a time, not five in a weekend.
- Ignoring the alerts. Automation is not “fire and forget” — glance at the weekly summary.
- Chasing every new app. A tool you never open cannot help you.
- Forgetting the emergency buffer. Keep enough in checking so auto-transfers never bounce.
Layering Automation Over Time
The most durable systems are built in stages, not overnight. In your first month, automate a single savings transfer and nothing else. Let it prove itself against a full billing cycle so you trust the rhythm of money leaving and bills still clearing.
In month two, add auto-pay on your recurring bills once you are confident the savings transfer never bounces. By month three, switch on round-up investing so spare change starts compounding quietly in the background. Only in month four should you introduce a subscription tracker to audit the recurring charges you have accumulated.
This staggered rollout matters because every new automation changes your available cash. Adding them one at a time lets you feel the impact of each change and adjust the amounts before layering on the next. People who try to automate everything in a single weekend almost always overshoot their real cash flow and abandon the whole system within a month. Slow and deliberate wins the automation game.
Frequently Asked Questions
Are money apps safe for automating my finances?
Yes, when you choose established apps that use bank-grade encryption, read-only account links, and two-factor authentication. Always verify the provider and enable every available security setting.
How much should I automate saving each month?
A common target is 20% of income, but starting at 5% and increasing it gradually is far better than waiting until you can afford the “ideal” amount. Consistency beats size early on.
Can automation hurt me if my income is irregular?
It can if you set fixed amounts too high. For variable income, use a percentage-based rule or automate transfers only after each deposit clears, so you never trigger an overdraft.
How many money apps should I really use?
Two or three is plenty for most people: one budgeting hub, one savings automation, and optionally a subscription tracker. More tools usually mean more clutter, not more wealth.
The Takeaway
Wealth is built quietly, one automated decision at a time. The right money apps turn your good intentions into background processes that run whether you feel motivated or not. Start with a single automated transfer this week, protect it with the 48-hour rule, and let the system compound. In 2026, the smartest financial move is not trying harder — it is removing yourself from the loop and letting automation do the heavy lifting.